

OneBlinc - Financial tools analysis by Appwee
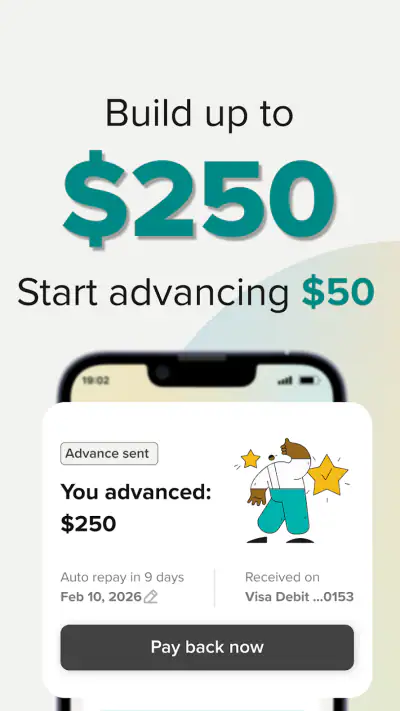
When an unexpected bill arrives before payday, the problem is often timing rather than a complete lack of money. OneBlinc is a finance app from OneBlinc built around that situation, giving eligible users a way to access wages through a linked account. I found its purpose easy to understand: it is not trying to replace a full banking app, investment platform, or budgeting suite. Its focus is short-term access to earned pay, with the store summary describing access to up to 250 dollars.
That narrow focus is also the key to judging it fairly. I would not install this expecting detailed spending analysis, long-term savings tools, or a complete financial dashboard. I would consider it when a small cash-flow gap matters and I want to examine the available terms before deciding whether early access is worthwhile. The app is free to download, and its content rating is Everyone, but free access should not automatically be confused with free money or with every possible transaction being costless.
How OneBlinc fits into everyday money management
In my experience, the most useful way to think about OneBlinc is as a bridge between work income and the date that income normally becomes available. That makes it different from a conventional checking account, where the main job is holding and moving money, and different from a budgeting app, where the main job is helping you understand spending. Here, the central question is whether accessing wages earlier solves a specific, short-lived problem.
A realistic example would be a utility payment due tomorrow while your regular payday is still several days away. Instead of immediately turning to a credit card or a general-purpose borrowing option, you could open the app, connect the relevant account, review what access is available, and decide whether the convenience is worth the obligation that follows. That last step matters. Early access can relieve pressure today while making the next pay cycle feel tighter if it becomes a habit.
The product is listed as a finance app rather than a broad banking replacement, and that distinction helps set expectations. I would use it alongside my normal bank account, not in place of it. My bank would remain the place for ordinary deposits, bill payments, and account history; OneBlinc would have a more specific role when timing is the issue.
What the free download does and does not mean
The app itself is free, which removes an obvious barrier to trying it. That is useful because the decision should be based on the actual access terms shown during the process, not on a download charge. I would still read every screen that explains repayment, eligibility, timing, and any applicable cost before confirming anything. A free app can still connect you to a financial service with terms that deserve careful attention.
I also would not assume that the headline amount is guaranteed for every person or every situation. The store summary presents access to wages up to 250 dollars, but a maximum is not the same as an automatic entitlement. What appears for an individual user can depend on the account connection and the app’s assessment. The practical lesson is simple: open the relevant details before planning a bill around a particular amount.
Because no purchase price is attached to the download, OneBlinc is easy to test without paying just to install it. That makes it more approachable than a paid financial tool. Still, I would separate three questions: can I install it without charge, can I qualify for the service, and what will the specific transaction cost or require? Those are different questions, and treating them as one could lead to a poor decision.
The first setup deserves more attention than it seems
The linked-account step is more important than a quick registration screen. I would check that I am selecting the correct account, that the account is active, and that the information shown afterward makes sense. A rushed connection can create confusion later, especially if someone has several accounts or receives income through more than one route.
I would also prepare to verify identity and income-related details if the app requests them. That is normal for a financial service, but it means setup may not feel as instant as opening a weather or messaging app. Anyone who needs money immediately should avoid waiting until the last possible minute to discover that a connection needs attention or that a review is required.
One practical habit I would recommend is taking a moment to note the expected repayment or deduction timing before accepting access. Even if the amount is small, the date can be more important than the amount. A user who only checks “how much can I receive?” may overlook “when will this affect my available money again?”
Where the app can deliver real value
OneBlinc’s value comes from reducing friction during a narrow but common cash-flow problem. If a modest expense would otherwise trigger an overdraft, a late payment, or expensive revolving debt, early wage access may be useful. The benefit is not that the user has earned more; the benefit is that money already connected to work income may become available at a more helpful moment.
That makes the app particularly relevant for people whose pay schedule does not line up well with recurring bills. A rent-related fee, transport expense, prescription, or urgent household purchase can arrive on an inconvenient day. In those cases, the app can be considered as one option among several, provided the user understands the effect on the next pay cycle.
I also see value in the app’s focused design. A person facing a short-term gap may not want to learn a large financial platform with savings goals, investment screens, and unrelated features. OneBlinc’s purpose is easier to grasp. That clarity can help someone make a decision more quickly, although speed should never replace reading the actual terms.
The app has reached more than 100K installs and holds a 4.6 average from around 4.8K ratings, which suggests that many people find the basic concept useful. I treat those figures as a sign of user interest rather than proof that the service will fit every financial situation. A high average can tell me that the general experience works for many users; it cannot decide eligibility, cost, or suitability for me.
Three less-obvious ways to use it responsibly
First, I would treat OneBlinc as a planned emergency tool rather than as part of normal weekly spending. Before requesting access, I would write down the exact bill, the amount needed, and the money expected to remain after the next pay event. This simple check prevents a small advance from becoming an untracked cycle of repeated use.
Second, I would compare the app with the cost of the alternative I am actually considering, not with an imaginary perfect solution. If the choice is between early wage access and a costly overdraft, the comparison should include timing and the consequences of each option. If the choice is between OneBlinc and simply waiting two days for payday, waiting may be better. The app’s usefulness depends on the real alternative, not on the headline convenience.
Third, I would use the linked-account review as a recurring safety check. If income patterns change, an account is closed, or the wrong account becomes connected, I would stop and update the situation before requesting anything. This is a small workflow improvement, but it reduces the risk of making a decision based on outdated account information.
Where the experience may feel limited
The biggest limitation is scope. Someone looking for a complete personal-finance system will likely find OneBlinc too focused. It is not the app I would choose for tracking categories of spending, planning investments, comparing savings accounts, or building a detailed monthly budget. A bank app or dedicated budgeting service is better for those jobs.
There is also a behavioral trade-off. Accessing wages early can solve a genuine timing problem, but repeated use can hide a structural shortfall. If every pay cycle requires money before payday, the app may provide temporary relief without fixing the underlying budget. I would see that pattern as a signal to review bills, income timing, and recurring expenses rather than simply requesting access again.
Another point of friction is that a linked account introduces a setup decision that deserves care. Users who are uncomfortable connecting financial accounts may prefer a different solution, even if OneBlinc appears convenient. I would not rush through permissions, identity checks, or explanations simply because the amount involved is modest.
The maximum described by the store summary is also limited enough that it will not solve every emergency. A larger expense may require a different source of funds, a payment arrangement, or help from a bank or provider. I would avoid treating the app as a general emergency fund. Its strongest use is a contained gap, not a major financial crisis.
Who is most likely to benefit
I think OneBlinc is most suitable for an adult who receives wages through a compatible linked account, understands the next pay cycle, and needs a small amount for a specific short-term expense. The Everyone content rating makes the app broadly labeled for general audiences, but financial responsibility still depends on the individual’s circumstances and ability to manage repayment.
It may also suit someone who prefers a focused tool over a full bank product. If the only question is “can I access part of my earned pay before the usual date, and what will that involve?”, a specialized app can be easier to navigate than a platform filled with unrelated financial features.
I would be more cautious for anyone already relying on advances, overdrafts, or credit to cover ordinary necessities. In that situation, OneBlinc may still be worth examining, but only as part of a wider plan. It should not be viewed as evidence that the budget is working when the same gap returns every month.
I would skip it if I need long-term borrowing, a large amount, investment guidance, or detailed financial planning. I would also skip it if I am unwilling to review linked-account details and transaction terms. A free download is not a reason to accept a financial arrangement without understanding it.
How it compares with ordinary alternatives
A traditional bank is more versatile for everyday money management. It usually makes more sense when I need deposits, transfers, bill payments, and a complete account history in one place. OneBlinc has a narrower advantage: it addresses the timing of wage access rather than replacing ordinary banking.
A budgeting app is better when the real problem is not the date of payday but the lack of visibility into spending. If I keep running short because subscriptions, food, transport, and bills are not being tracked, budgeting software can offer more lasting value. OneBlinc can help with today’s timing issue, but it does not substitute for understanding where money goes.
A credit card may offer broader purchasing flexibility, but it can also encourage a balance to remain unpaid. A personal loan may handle a larger planned expense, but it is excessive for a small, temporary gap. Waiting for payday costs nothing in financial access terms, although it may be impractical when a payment is urgent. The right choice depends on the size of the need, the timing, and the terms visible to the user.
That comparison is why I would not call OneBlinc universally better than the alternatives. Its value is strongest when the amount is modest, the income is expected, and the cost of the alternative is worse. If those conditions are missing, another option may be safer or more appropriate.
What the current app details suggest
OneBlinc was released on February 18, 2025, and the current version is 7.12.0. The listed minimum operating system is Android 7.0, so users on older Android devices should check compatibility before planning to rely on it. I would also keep the app updated because financial tools need a stable connection and clear account information, even though an update alone does not change the need to review terms.
The developer is OneBlinc, the same name used for the app. That makes the product identity straightforward when checking the installation screen or looking for support inside the proper app listing. I would still make sure I am installing the genuine application rather than an imitation with a similar name, especially because finance apps handle sensitive information.
The review count is around 672, while the broader rating count is around 4.8K. I find that combination useful as a general confidence signal, but I would read recent comments with a specific question in mind: are people describing a smooth experience for my type of account and need? Reviews can reveal recurring friction, yet they cannot guarantee that my eligibility or terms will match another person’s.
My practical decision process
If I were deciding whether to use it tonight, I would begin with the bill rather than the app. I would confirm the exact amount, the deadline, and whether the provider offers an extension or another no-cost arrangement. Then I would open OneBlinc only if early access still appeared useful, connect the correct account carefully, and inspect the available amount and terms.
Before confirming, I would ask myself whether the next pay cycle can absorb the deduction or repayment without creating a second emergency. If the answer is no, I would not proceed simply because the app makes access possible. Convenience is valuable only when it does not move the same problem a few days forward.
After using the service, I would record the date and amount in my normal budget. That prevents the transaction from disappearing from view and makes it easier to judge whether OneBlinc solved an isolated timing issue or has become part of a repeating pattern. This small record is more useful than relying on memory.
My verdict for potential users
I see OneBlinc as a focused, free-to-download finance app with a clear use case: helping eligible users consider earlier access to wages through a linked account. Its strongest qualities are its narrow purpose, approachable entry point, and usefulness when a small payment cannot wait for the normal payday. The store’s 4.6 average from around 4.8K ratings and more than 100K installs support the view that it has attracted meaningful interest, but those figures should not replace personal judgment.
My recommendation is conditional: try it when the need is specific, the next pay cycle is understood, and the displayed terms make sense. I would not recommend using it as a routine substitute for budgeting, savings, or stable income. The app can be a practical bridge, but a bridge is most helpful when I know where I am going and how I will reach the other side.
For someone facing a one-off cash-flow mismatch, OneBlinc is worth examining because the download is free and the purpose is easy to understand. For someone seeking a full financial home, a long-term loan, or a solution to recurring overspending, I would choose a bank, budgeting tool, or professional financial guidance instead. That distinction is what gives OneBlinc its real value: not as an answer to every money problem, but as a targeted option for the right short-term situation.
Gallery
OneBlinc - Financial tools Pros and Cons
- Early paycheck access can help cover urgent expenses before payday.
- Personalized financial tools encourage better money management habits.
- Simple mobile interface makes account features easy to navigate.
- May offer alternatives for users with limited traditional banking options.
- Security features help protect personal and financial information.
- Fees and eligibility requirements may vary by user and transaction type.
- Cash advances can encourage repeated borrowing between paychecks.
- Not all employers or income sources may qualify for its services.
- Some features may require recurring membership or subscription payments.
- Availability and terms can differ depending on your location.
OneBlinc - Financial tools Frequently Asked Questions
What is OneBlinc, and what financial tools does it offer?
OneBlinc is a financial services app designed to help eligible users manage short-term cash flow and everyday money needs. Depending on availability, its tools may include paycheck advances, a spending account or card, budgeting features, credit-building services, and other financial products. The exact features, limits, fees, and eligibility requirements can vary, so review the terms shown in the app before accepting any offer.
Who can use OneBlinc, and what are the eligibility requirements?
OneBlinc is not automatically available to everyone. Eligibility may depend on factors such as your age, location, identity verification, employment or income information, recurring direct deposits, and other account or underwriting criteria. During registration, the app may request permission to verify financial information. Meeting the basic requirements does not guarantee approval, a specific advance amount, or access to every feature.
Does OneBlinc charge fees or interest?
The cost of using OneBlinc depends on the particular product and the terms presented to you. Some services may involve membership charges, expedited-transfer fees, card-related fees, or other costs, while an advance may have different pricing from a traditional loan. Before confirming a transaction, carefully check the fee disclosure, repayment date, subscription details, and any applicable terms so you understand the total amount involved.
How does repayment work if I use a OneBlinc cash advance?
If you receive a cash advance through OneBlinc, repayment is generally scheduled for a future date and may be collected from a linked bank account or another payment method. The app should display the repayment amount and expected date before you confirm. Make sure sufficient funds are available, because a failed payment could lead to additional fees, account restrictions, or other consequences under the applicable agreement.
Is OneBlinc safe to use, and what should I know about privacy?
OneBlinc may require sensitive information such as your identity details, bank-account data, income information, and transaction history to provide or evaluate its services. Use the official Android or iOS listing, verify the developer name, and read the privacy policy before connecting an account. No financial app is completely risk-free, so enable device security, protect your login credentials, and monitor account activity regularly.














